Welcome to our live ASX coverage for Friday, October 23. Expect a high volume of posts pre-market and more periodic updates throughout the day. We’ll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX miners near 7-month low
[11:58 am] It’s absolute carnage out there for resources. The S&P/ASX 200 Materials Index is down 3.0% to the lowest since 30 March and now up just 1.4% for the year (compared to ~24% YTD gains just 7 weeks ago). Nothing is safe today, with declines spanning lithium, copper, gold, rare earths, iron ore and more.
|
LTR |
Liontown |
-6.2% |
$0.65 |
-7.5% |
-58.8% |
|
SFR |
Sandfire Resources |
-5.8% |
$18.68 |
-8.9% |
4.0% |
|
IGO |
IGO |
-5.6% |
$4.86 |
-11.8% |
-40.7% |
|
PLS |
PLS Group |
-5.6% |
$2.69 |
-14.6% |
-36.0% |
|
CMM |
Capricorn Metals |
-5.4% |
$12.73 |
-10.7% |
-9.1% |
|
PRU |
Perseus Mining |
-5.2% |
$5.48 |
-11.0% |
-0.5% |
|
S32 |
South32 |
-4.8% |
$4.15 |
-9.2% |
16.9% |
|
LYC |
Lynas Rare Earths |
-4.7% |
$10.85 |
-3.1% |
-12.6% |
|
GMD |
Genesis Minerals |
-4.6% |
$6.38 |
-10.1% |
-11.0% |
|
CIA |
Champion Iron |
-4.1% |
$2.23 |
-7.7% |
-63.3% |
|
ILU |
Iluka Resources |
-3.7% |
$5.00 |
-3.7% |
-13.6% |
|
MIN |
Mineral Resources |
-3.5% |
$42.68 |
-4.7% |
-21.5% |
|
BHP |
BHP Group |
-3.1% |
$55.37 |
-7.1% |
21.6% |
|
NIC |
Nickel Industries |
-3.0% |
$0.65 |
-9.1% |
-26.1% |
|
SGM |
Sims |
-2.9% |
$19.58 |
-7.3% |
8.9% |
Australia’s private sector shrinks as price pressures intensify
[11:30 am] Australia’s private sector slipped back into contraction in October, with S&P Global’s flash PMI showing services joining manufacturing in decline as inflation pressures built.
-
The flash Composite PMI fell to 47.7 from 51.3 in September, the first contraction in private sector output in five months and the lowest reading since March
-
The services PMI fell to 47.8 from 51.9, its first decline since May
-
The manufacturing PMI edged up to 49.7 from 49.6, while the manufacturing output index stayed deep in contraction at 46.5
-
New orders growth slowed to near-neutral, with firms citing weak confidence, rising borrowing costs and inflation
-
Input cost inflation hit its fastest pace since May on higher energy, shipping, commodity and wage costs, with output price inflation rising for a second month
-
S&P Global’s Jingyi Pan said inflation “could remain elevated in the coming months”, which “could further pose a threat to demand in the near-term”
Source: S&P Global
Temple & Webster surges as sales trends improve
[11:29 am] Temple & Webster shares are up 28% to $5.21 as we approach noon after today’s trading update showed sales trends improving since August.
-
Run-rate revenue growth improved to -4% since the August update, from -13%
-
Contribution margin dollars rose 16% for 1 July to 19 October, despite revenue falling 8%
-
FY27 EBITDA guidance of $33m to $40m reaffirmed, with the $36.5m midpoint 7% above ests
-
A return to revenue growth is expected from mid-February
Company page: Temple & Webster (TPW)
Brokers question Zip’s controls after US fraud hit
[11:28 am] Analysts are questioning Zip’s customer onboarding controls after an external US fraud event weighed on its September quarter, sending shares down as much as 49% at the open.
-
Citi said the incident “raises concerns on Zip’s onboarding controls”
-
Jefferies said investors need clarity on whether the increase in operating expenses will persist and how Zip plans to prevent similar incidents
-
UBS flagged net bad debts as a key miss, with the ratio rising to 1.97% vs its 1.80% estimate
-
UBS said the sharper rise was partly due to the fraud event temporarily slowing TTV growth in July and August
Company page: Zip Co (ZIP)
Zip plunges 49% at the open before staging a sharp rebound
[11:25 am] What an insane move for Zip, after an external US fraud event dented its September quarter.
-
Zip opened 49% lower at $1.06 before rallying more than 40% to $1.50 within the first seven minutes of trade, and is now down 30% at $1.44
-
Cash EBTDA of $65.0m vs $76.9m ests (15% miss), including $10.1m of costs from the US fraud event
-
Net bad debts rose to 1.97% of TTV vs 1.80% ests, though Zip expects lower US bad debts in 2Q27
-
The fraud event slowed US transaction volume and new customer growth in July and August, before US TTV growth recovered to 41% in USD in September
-
Total transaction volume up 18% to $4.6bn vs $4.66bn ests (1% miss)
-
FY27 cash EBTDA guidance of $340m reaffirmed
Company page: Zip Co (ZIP)
Santos enters harvest phase as free cash flow inflects
[11:21 am] Macquarie says Santos has entered a harvest phase after its long-awaited cash flow inflection, with a final investment decision on Papua LNG the next key milestone.
-
All-in free cash flow of US$957m in the third quarter, driven by new project start-ups and supportive pricing
-
Alaska’s Pikka project briefly hit its 80kb/d plateau before weather and a third-party pipeline incident disrupted output, with plateau now expected early in 4Q
-
4Q Alaska production forecast cut to 2.7MMboe vs 3.1MMboe ests
-
Barossa feed gas to Darwin LNG peaked at 600MMscf, with 12 cargoes delivered in the quarter
-
Papua LNG FID is likely within one to two months, ahead of the PNG government’s 15 December deadline
-
Outperform rating maintained, with the target to $9.50 from $9.55 and the stock implying an oil price of US$66.7/bbl
Company page: Santos (STO)
Fortescue warns of production cuts if China iron ore impasse drags on
[11:18 am] Macquarie says Fortescue’s warning that it may cut output if talks with China Mineral Resources Group (CMRG), Beijing’s state-backed iron ore buyer, aren’t resolved by year-end was the key takeaway from its quarterly.
-
1Q27 Ore mined of 62.7Mt beat ests by 7% despite the port shutdown
-
1Q27 C1 costs of US$21.98/wmt came in 2% below ests, despite a roughly US$1.40/wmt diesel headwind
-
1Q27 sales trailed shipments by 3.9Mt due to CMRG restrictions, with a further 4Mt to 5Mt inventory build expected in October alone
-
Production may be cut if there’s no CMRG deal by calendar year-end, putting 2H FY27 sales and earnings at risk
-
Curtailing 25Mt in 2H could cut EBITDA by about US$1bn, though the broker expects a deal to be reached
-
Outperform rating maintained, with the target to $18 from $19 after EPS cuts of 6% to 11% over FY27 to FY30
Company page: Fortescue (FMG)
NAB’s capital buffer in focus ahead of bank reporting season
[11:17 am] Morgan Stanley, which retains a Cautious view on the sector, expects capital and dividends to be in focus at the major banks’ upcoming results, with NAB facing the most scrutiny.
-
Capital buffers above CET1 targets are estimated at about $2.4bn at ANZ, $2.2bn at Westpac and $0.6bn each at CBA and NAB
-
FY26 underlying payout ratios are forecast at about 74% for NAB and 75% for Westpac, at the top end of their 65% to 75% target ranges
-
Reported capital ratios could disappoint given higher interest rate risk in the banking book, strong non-housing loan growth and potentially higher credit risk weightings
-
NAB raised $1.8bn via partial DRP underwriting after its capital ratio fell short in May, and now has a modest buffer and elevated payout
-
Westpac’s strong buffer should allow it to hold its dividend, while CBA’s CET1 ratio could be at its lowest since 1Q23 due to its dividend skew
-
The base case is flat dividends and no new capital management, though the risk of dividend cuts rises in FY27
Top ASX 200 gainers
[11:04 am] Nick Scali is bouncing after yesterday’s earnings downgrade, while the broader retail sector also catches a bid. Charter Hall (one of the more sensitive REITs to the 10-year) is also trading notable higher, and defensives like banks, healthcare and telcos also catch a bid.
|
NCK |
Nick Scali |
3.9% |
$12.50 |
-13.7% |
-46.8% |
|
JBH |
JB Hi-Fi |
3.3% |
$74.05 |
2.7% |
-23.1% |
|
RMD |
Resmed |
3.2% |
$35.94 |
3.6% |
-0.5% |
|
CHC |
Charter Hall Group |
3.1% |
$20.13 |
6.9% |
-17.7% |
|
COH |
Cochlear |
3.0% |
$144.86 |
11.2% |
-44.5% |
|
AMC |
Amcor |
2.9% |
$65.98 |
6.0% |
5.5% |
|
WES |
Wesfarmers |
2.7% |
$79.44 |
0.7% |
-2.0% |
|
SUL |
Super Retail Group |
2.6% |
$13.64 |
0.2% |
-14.7% |
|
PMV |
Premier Investments |
2.6% |
$13.72 |
8.5% |
-0.9% |
|
JHX |
James Hardie |
2.2% |
$37.68 |
1.6% |
21.5% |
Top ASX 200 losers
[11:04 am] Zip opened 49.0% lower at $1.06 and is still the market’s worst performer, but it has since clawed back 38% from those lows. Meanwhile, the entire commodity complex is in the red, with energy, lithium, gold, copper and uranium stocks all lower.
|
ZIP |
Zip Co |
-28.5% |
$1.48 |
-31.5% |
-54.7% |
|
OBM |
Ora Banda Mining |
-15.8% |
$1.12 |
-18.2% |
-26.8% |
|
MP1 |
Megaport |
-6.6% |
$15.78 |
-2.2% |
39.0% |
|
FFM |
Firefly Metals |
-5.9% |
$1.27 |
-9.0% |
-38.3% |
|
ELV |
Elevra Lithium |
-5.9% |
$3.53 |
-13.1% |
-56.0% |
|
KAR |
Karoon Energy |
-5.8% |
$1.62 |
-3.9% |
5.2% |
|
MI6 |
Minerals 260 |
-5.4% |
$0.70 |
-10.9% |
65.5% |
|
DYL |
Deep Yellow |
-5.2% |
$0.68 |
-18.4% |
-63.2% |
|
PDI |
PDI Gold |
-5.2% |
$3.64 |
-13.3% |
-0.3% |
|
RSG |
Resolute Mining |
-5.2% |
$1.06 |
-5.2% |
-13.7% |
Elixir farms out half its Taroom Trough stake to Beach in $205m deal
[9:52 am] Queensland gas explorer Elixir Energy has brought in Beach Energy as a partner on its Taroom Trough permits, a basin-centred gas play in the Bowen Basin near the Wallumbilla gas hub.
-
Beach will acquire half of Elixir’s working interests and operatorship across its Taroom Trough permits, excluding the Diona JV sub-block
-
Consideration totals $205m, comprising $25m in cash and $180m of carried appraisal drilling, studies, seismic and operating costs over four years
-
The carry provides a funding pathway for about four years, substantially reducing the capital required from shareholders
-
The deal values Elixir’s 2C contingent gas resources at about $118,700 per BCFe, which management says is 3x their current trading value
-
Elixir retains about 1,200km² of net Taroom Trough acreage, including its operated position in the Diona JV
-
An area of mutual interest agreement lets either party join newly acquired acreage on a 50:50 basis, or new acreage bids on a 65:35 basis, with Beach as operator
A little suspicious that Elixir rallied 25.4% on Thursday, despite the broader S&P/ASX 200 Energy Index tanking 2.4%. The stock opened the session 7.2% higher (5.9 cents) and rallied intraday to close at best levels.
Company page: Elixir Energy (EXR)
Nido buys nine Edge Early Learning centres in first acquisition
[9:49 am] Childcare operator Nido Education has made its first acquisition, buying nine early learning services from Edge Early Learning.
-
The deal is the first under Nido’s strategy to selectively acquire established services, outlined in April 2026
-
Acquisitions will complement its greenfield incubation model, which remains core to its growth strategy
-
Financial terms were not disclosed
-
Completion is subject to regulatory approvals and the assignment of the relevant leases
-
Nido will keep assessing further opportunities that meet its investment criteria
Company page: Nido Education (NDO)
A sea of red for commodities
[9:42 am] Commodities (ex-Energy) traded broadly lower as a deepening selloff in AI-linked stocks sapped risk appetite, with investors favouring treasuries over precious metals as a safe haven and copper also weighed down by a surge in LME inventories.
-
Silver fell 5.8% to US$54.60/oz
-
Platinum fell 3.9% to US$1,566.20/oz
-
Palladium fell 3.4% to US$1,052.39/oz
-
Gold fell 2.8% to US$4,025.19/oz
-
Copper fell 2.7% to US$6.46/lb
-
Nickel fell 1.8% to US$15,924/t
-
Aluminium fell 0.7% to US$2,991.80/t
This drove a broad-based selloff across resource-related ETFs overnight, including:
|
SIL |
Global X Silver Miners |
-6.6% |
$75.99 |
-18.7% |
-11.3% |
|
COPX |
Global X Copper Miners |
-6.3% |
$73.13 |
-17.3% |
-0.6% |
|
GDX |
Vaneck Gold Miners |
-5.8% |
$81.69 |
-13.6% |
-6.2% |
|
URA |
Global X Uranium |
-4.1% |
$34.09 |
-21.5% |
-21.6% |
|
LIT |
Global X Lithium & Battery Tech |
-4.0% |
$60.68 |
-14.1% |
-7.9% |
|
REMX |
Vaneck Rare Earth And Strategic Metals |
-3.3% |
$51.60 |
-26.8% |
-31.2% |
|
SLX |
Vaneck Steel |
-3.3% |
$99.96 |
-5.8% |
16.6% |
|
NIKL |
Sprott Nickel Miners |
-1.5% |
$11.22 |
-21.6% |
-31.7% |
Swoop sells Sydney fibre assets for $4.5m to cut debt
[9:35 am] Telecommunications provider Swoop Holdings is selling non-core fibre assets to sharpen its focus on its consumer telco businesses.
-
Swoop has signed a binding agreement to sell its Sydney-based fibre assets to Xenith Infrastructure Group for about $4.5m
-
Net proceeds will go towards debt reduction and general working capital
-
Completion is expected in Q3 FY27, subject to conditions including FIRB approval
-
The sale is not expected to affect Swoop’s ongoing operations or continuity of customer services
Swoop trades at a market cap of $20.5m, with a net debt position of $13.7m at 30 June 2026 (borrowings of $22.5m less $8.9m cash). The company sold its Melbourne fibre network in June, with completion anticipated in 1H27, releasing ~$11m cash. The Sydney assets will release a further ~$4.5m, which should bring the company into a slight net cash position.
Company page: Swoop Holdings (SWP)
Whitehaven costs track low end of guidance as port disruptions delay sales
[9:33 am] Whitehaven Coal made a strong start to FY27 on production and costs, though export terminal disruptions pushed some sales into the December quarter.
-
Managed ROM production up 22% year-on-year to 11.0Mt, and up 3% on the June quarter
-
Equity sales of produced coal down 5% quarter-on-quarter to 6.0Mt, after disruptions at the RG Tanna (Gladstone) and Port Waratah (Newcastle) coal terminals
-
Average achieved price up 20% year-on-year to $226/t, and up 2% on the June quarter
-
QLD averaged $257/t, with 12-month met coal realisations at 74% of the benchmark index, while NSW achieved $198/t at 103% of the thermal index
-
Unit costs came in at the low end of FY27 guidance of $132 to $147/t, despite elevated diesel costs
-
Net debt of about $1.4bn, with the impact of sales slippage and elevated inventories expected to unwind in the December quarter
Company page: Whitehaven Coal (WHC)
Acusensus lands ACT traffic camera deal worth up to $210m
[9:28 am] AI road safety technology company Acusensus has expanded its role in the ACT from phone and seat belt detection to full traffic enforcement under a new long-term contract.
-
The initial five-year term is worth about $63m (excluding GST), rising to an estimated $210m if two further five-year options are exercised
-
The contract adds red-light, speed and average speed enforcement to its existing mobile phone and seatbelt detection in the territory
-
Services include fixed and transportable cameras, plus mid-office software for the ACT to run its adjudication processes
-
The staged rollout is expected to begin in mid-2027
-
The ACT joins WA in using its full multifunction camera suite, with Acusensus also holding enforcement contracts in NSW, Queensland and SA
Company page: Acusensus (ACE)
Fenix cashes in $10m iron ore hedge book as prices slide
[9:27 am] WA iron ore miner Fenix Resources has closed out its iron ore hedges early, locking in gains from the recent slide in prices and leaving it fully exposed to spot iron ore.
-
Fenix closed out its iron ore swap book, covering 480,000 tonnes hedged at an average $151.31/t from October 2026 to June 2027
-
The early settlement crystallises more than $10m, including about $8.5m for November to June contracts received in October and about $1.7m for October contracts settling in November
-
The Platts 61% index averaged US$96.90/t in the September quarter, or about $137.22/t in Australian dollar terms, well below the hedged price
-
Remaining diesel swaps cover 13.5 million litres, about 30% of expected FY27 usage, with a mark-to-market value of about $5.6m
-
Currency call options cover US$99m through to June 2028 at an average AUD/USD exercise price of 0.7532, valued at about $0.5m
Company page: Fenix Resources (FEX)
Alkane costs come in below ests as maiden dividend paid
[9:25 am] Gold and antimony producer Alkane Resources delivered lower costs than UBS expected, with strong cash generation funding its first shareholder returns.
-
Gold equivalent production of 40.7koz (pre-reported), annualising to the bottom of FY27 guidance of 163koz to 177koz
-
AISC of A$2,805/oz vs A$2,940/oz ests (5% beat), below FY27 guidance of A$2,900-3,200/oz
-
Mine operating cash flow of $102m, on an average gold sales price of $5,128/oz
-
Cash, bullion and listed investments of $459m after $13m of tax payments, with a further $55m to $60m in FY26 tax due in the December quarter
-
Maiden fully franked dividend of 2cps paid
-
A $50m buyback was approved in September
Company page: Alkane Resources (ALK)
Zip fraud hit puts record short interest in focus
[9:24 am] The US fraud event appears to have tempered Zip’s September quarter, and possibly its near-term growth, while taking a hefty toll on earnings. That could stir up some volatility in the stock, with short interest at a record 13.39%, making Zip the fourth most shorted stock on the ASX.
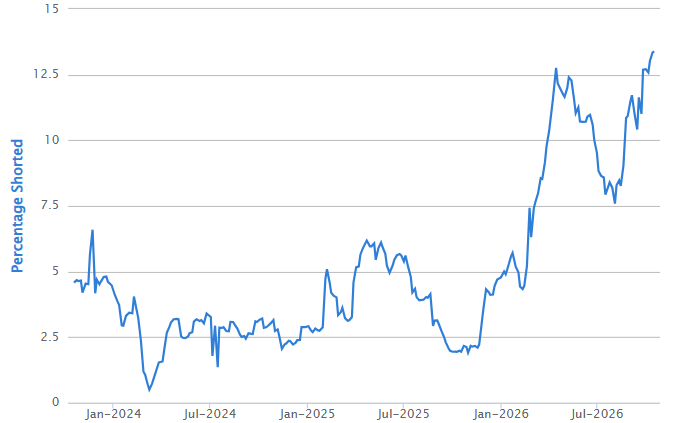
Zip short interest chart (Source: Shortman)
Zip bad debts top ests as US fraud event dents earnings
[9:18 am] Zip’s top line landed broadly in line with UBS ests, but net bad debts ran hotter than expected after an external fraud event in the US.
-
Total transaction volume up 18% to $4.6bn vs $4.66bn ests (1% miss)
-
US transaction volume up 34.1% in USD vs ests of 35%, with September growth of 41% once the fraud event was contained
-
Total income up 17% to $376.1m vs $369.2m ests (2% beat)
-
Active customers of 6.4m vs 6.67m ests (4% miss), with the fraud event temporarily slowing new US customer growth in July and August
-
Net bad debts rose to 1.97% of TTV from 1.65% in 1Q26 vs 1.80% ests, with Zip forecasting lower US bad debts in 2Q27
-
Cash EBTDA up 3.4%to $65.0m vs $76.9m ests (15% miss), or up 19.5% to $75.1m excluding $10.1m of US fraud costs (2% miss)
-
FY27 cash EBTDA guidance of $340m reaffirmed, alongside US TTV growth above 30% in USD and an operating margin of 20% to 22%
Company page: Zip Co (ZIP)
Temple & Webster sales decline narrows as margins climb
[9:16 am] Temple & Webster’s new CEO said trading has improved since August as the online furniture retailer pulls back on discounting, with FY27 EBITDA guidance sitting above UBS ests.
-
Revenue down 8% for 1 July to 19 October, vs ests of a 9% decline for 1H, after deliberate cuts to promotional depth
-
Contribution margin dollars up 16% over the same period
-
Run-rate revenue growth improved to -4% since the August update, from -13%
-
A return to revenue growth is expected from mid-February, when it starts cycling periods with similar promotional intensity
-
FY27 EBITDA guidance of $33m to $40m reaffirmed, with the $36.5m midpoint 7% above ests
-
A refreshed brand campaign in Brisbane lifted traffic 11% and revenue 7% vs control markets, and is now rolling out to Sydney and Melbourne
Company page: Temple & Webster (TPW)
Bhagwan Marine revenue jumps 32% as Riverside acquisition kicks in
[9:14 am] Marine services provider Bhagwan Marine told its AGM it had made a strong start to FY27, though most of the growth came from its Riverside Marine acquisition rather than the core business.
-
Core group revenue up 32% to $81.3m year-on-year, and up 14% on the June quarter
-
Bhagwan Marine revenue up 3% to $63.7m year-on-year, and up 14% on the June quarter
-
Riverside Marine revenue up 14% on the June quarter to $17.6m, and up 6% year-on-year
-
Recurring revenue rose to 64% of group revenue, from 62% on an FY26 pro forma annualised basis
-
High-margin Offshore Energy & Resources (subsea) and Riverside Industrial Sands were the standout contributors
Company page: Bhagwan Marine (BWN)
Ora Banda misses on output as mill shutdown and weather lift costs
[9:09 am] Ora Banda’s September quarter fell short of UBS ests on both production and costs, with an extended mill shutdown and wet weather weighing on output.
-
Gold production of 33.3koz vs 40koz ests (17% miss)
-
AISC of $4,214/oz vs $3,870/oz ests (9% miss)
-
FY27 guidance maintained, with MD Luke Creagh saying weather and mill downtime are “expected to be limited to the September quarter”
-
Closing cash of $207m, with $83.3m in operating cash flow offset by $133.7m spent on exploration, development and growth
-
Liquidity of $507m after the revolving credit facility was upsized to $300m post quarter-end
-
Construction of the new 3.0Mtpa processing plant began on schedule and Waihi Underground mining started early, part of its aspiration to double output to 300koz in FY29
Company page: Ora Banda Mining (OBM)
Black Cat resets Kal East mine plans, holds FY27 guidance
[9:07 am] WA gold producer Black Cat Syndicate maintained FY27 guidance despite weaker-than-expected mine performance at Kal East, which prompted a reset of its Resources, Reserves and mine plans.
-
Attributable gold production of 16.7koz, or 19.2koz including third-party ore
-
Operating cash flow of $39m, down on the prior quarter due to lower-margin toll treating, bearing repairs at Lakewood and lower grades
-
Committed toll treating is set to end in the December quarter, which the company expects to drive a material uplift in operating cash flow in H2 FY27
-
Cash and liquid investments down 26% to $78m, mainly reinvested in Kal East mine development ($39m) and drilling ($10m)
-
Kal East Resources and Reserves were downgraded on grade after operating knowledge from the newly acquired deposits, with mine plans reset at quarter-end
-
FY27 guidance maintained at 80-90koz at AISC of A$3,500-3,900/oz, with Q1 AISC of A$3,735/oz sitting within the range
Company page: Black Cat Syndicate (BC8)
MinRes holds FY27 guidance as Onslow Iron costs beat
[9:06 am] Mineral Resources kept FY27 guidance unchanged across all divisions despite a softer realised iron ore price.
-
Onslow Iron attributable shipments of 5.0Mt wmt at an FOB cost of $53/wmt, below FY27 guidance of $54 to $58/wmt
-
Realised iron ore price down 5% quarter-on-quarter to US$83/dmt, an 85% realisation of the Platts 61% index
-
Record attributable lithium sales up 8% to 170k dmt SC6, though Bald Hill costs of $1,498/dmt ran well above guidance of $1,150 to $1,250/dmt
-
Mining Services production up 10% quarter-on-quarter to a record 103Mt
-
Net debt fell $200m to about $4.1bn, with liquidity of $2.5bn and Fitch upgrading its credit rating to BB from BB-
-
ASIC concluded its investigation into the company with no enforcement action
Company page: Mineral Resources (MIN)
Treasuries post best day in over a year as AI rout sparks haven rush
[8:59 am] The tech selloff stoked growth worries that outweighed inflation fears from higher oil prices, sending investors into US government debt.
-
The 10-year Treasury yield fell 15 basis points to 4.97%, back below 5% for the first time in a month, with some maturities down as much as 20bps
-
Traders scaled back Fed hike bets, now fully pricing a quarter-point increase by January rather than December
-
The five-year breakeven inflation rate is slightly below pre-war levels, suggesting the rise in yields since February has been driven by real rates rather than inflation
-
A $26bn five-year TIPS auction was awarded at 2.367%, the highest yield for that tenor since October 2023
-
French bond spreads widened to a 15-year high, with France’s 10-year yield above the US 10-year for the first time since 2013
-
ECB Governing Council member Fabio Panetta said rising yields are “not a crisis, but it is a drag on growth” for Europe
Brent jumps as US and Israel plan renewed Iran strikes
[8:58 am] Oil hit a five-month high after deadly attacks in Saudi Arabia and reports the US and Israel are preparing fresh strikes on Iran after the midterms.
-
Brent rose 2.8% to US$112.81, the highest since 5 May
-
The US and Israel have drawn up plans for a “short but intensive” operation against Iran after the 3 November midterms, the New York Times reported, though Trump has yet to approve them
-
A drone strike on Aramco’s Shaybah field killed two people but left its 1 million barrels a day of capacity unaffected, while an attack on Dammam’s airport also caused casualties
-
The US ordered some diplomats and their families out of Saudi Arabia due to the Houthi threat, while Aramco’s Dhahran headquarters was evacuated
-
Iran’s Revolutionary Guard said it struck four tankers in the northern Persian Gulf, while Iranian officials vowed to widen attacks to data centres and undersea internet cables
-
Gulf crude exports have recovered to near pre-war levels through Hormuz, though oil-product shipments remain constrained
-
Kpler expects Chinese crude demand to keep recovering, with stockpiles drawn down at a record 1.6 million barrels a day in September
Tesla falls 3% despite earnings beat as spending shifts to later years
[8:58 am] Tesla’s profit topped ests, but investors looked past the beat to heavier investment in robotics and autonomy over the next two years.
-
Revenue of $28.05bn vs $28.13bn ests (in line)
-
Adjusted EBITDA of $3.90bn vs $3.66bn ests (7% beat)
-
Adjusted EPS of $0.48 vs $0.44 ests (9% beat)
-
FY26 capex guidance cut to $20bn from $25bn, partly as Optimus robots need more training before release
-
Spending is set to rise in 2027 and 2028 on Optimus, Cybercab and Terafab, while elevated operating expenses weighed on the result
Moderna plunges 18% on possible melanoma vaccine data leak
[8:57 am] Moderna shares tumbled after details of its personalised melanoma vaccine appeared to leak ahead of a weekend presentation, with the results falling short of investor hopes.
-
Moderna fell 17.6% to $202.63 after dropping as much as 25% intraday, while partner Merck fell 1.8%
-
Unverified posts on X cited a 42% reduction in recurrence or death for the vaccine, intismeran autogene, when given with Merck’s Keytruda
-
TD Cowen’s Tyler Van Buren said the results reportedly showed a 38% reduction in the risk of the cancer spreading in high-risk patients vs standard treatment
-
An earlier study in a different patient group found a 49% reduction in recurrence or death, though it isn’t a direct comparison
-
Shares had more than doubled on the initial August announcement, which gave no detail on the results
-
Full data is due at the European Society for Medical Oncology conference in Madrid on Saturday
US IPO market stalls as AI jitters drain risk appetite
[8:56 am] The US listings pipeline has frozen outside of Anthropic’s expected November debut, as the AI selloff and higher rates sap investor appetite.
-
October is on track to be the slowest month of the year by US IPO volume, after $162.6bn was raised through September
-
Just US$587.7m has been raised via US IPOs since the end of September, excluding blank-cheque firms and other financial vehicles
-
Anthropic’s anticipated debut could raise as much as or more than SpaceX’s listing, according to people familiar with the matter
-
Data centre developers Nscale and DayOne are still pitching US listings, while smart-ring maker Oura and Bamboo Insurance have postponed debuts
-
Deloitte’s Will Braeutigam expects six or fewer companies to raise US$500m or more on US exchanges by year-end, with most clients focused on Q2
Source: Bloomberg
Copper slides as LME stockpiles surge and AI selloff weighs
[8:55 am] Copper extended its retreat from last month’s record as a jump in LME inventories added to pressure from the tech selloff.
-
LME copper fell 1.8% to US$14,105.50 a tonne after touching US$14,076, down from a record US$14,875 last month
-
LME on-warrant inventories jumped 70,100 tonnes over two days, mostly in the US, as backwardation encouraged delivery against short positions
-
Comex prices have fallen to near parity with the LME amid doubts the US will impose a tariff on refined copper
-
Workers at Teck’s Highland Valley Copper, Canada’s largest copper mine, are threatening to strike as early as Saturday
Newmont free cash flow misses by 43% despite earnings beat
[8:54 am] Higher gold prices lifted Newmont’s earnings above ests, but free cash flow fell well short.
-
Revenue up 15% to US$6.36bn vs US$6.31bn ests (1% beat)
-
Adjusted EBITDA of US$3.95bn vs US$3.78bn ests (4% beat)
-
Adjusted net income of US$2.31bn vs US$2.47bn ests (6% miss), excluding a $40m gain on asset sales
-
Adjusted EPS of US$2.20 vs US$2.11 ests (4% beat)
-
Free cash flow of US$1.91bn vs US$3.36bn ests (43% miss)
-
Attributable gold production of 1.30Moz at AISC of US$1,454/oz, with a realised gold price of $4,317/oz
-
FY26 production guidance of 5.3Moz on track, though Q4 AISC is guided to US$1,900/oz from US$1,454/oz in Q3
Spotify EPS misses by 12% despite margin expansion
[8:54 am] Spotify kept growing users and margins, but bottom-line earnings fell well short of ests, shares still rallied 11% to $583.66.
-
Revenue up 16% to €4.97bn vs €4.98bn ests (in line)
-
Monthly active users up 11% to 788m, with premium subscribers up 9% to 306m
-
Gross margin up 136bps to 33.0%
-
Operating income up 15% to €672m vs €680m ests (1% miss), with social charges €13m above forecast
-
Diluted EPS down 24% to €2.48 vs €2.81 ests (12% miss)
-
Q4 operating income guidance of €820m vs €813m ests (1% beat), with revenue guidance of €5.2bn vs €5.23bn ests (1% miss)
Meta profit misses on $9.9bn legal charge as capex guidance rises
[8:53 am] Meta’s core ad business delivered a revenue beat, but a one-off legal charge dragged profit well below ests. The stock fell 6.9% to $648.85.
-
Revenue up 26% to $64.60bn vs $63.33bn ests (2% beat), with average price per ad up 14%
-
Operating income of $12.99bn vs $18.66bn ests (30% miss), including a $9.9bn charge tied to an agreement with US State Attorneys General
-
EPS up 265% to $3.83 vs $5.89 ests (35% miss)
-
Free cash flow was negative $2.12bn as quarterly capex hit $34.91bn
-
Q4 revenue guidance of $73bn to $76bn, with the $74.5bn midpoint 1% above ests
-
FY26 capex guidance narrowed to $135bn to $145bn from $130bn to $145bn, with the $140bn midpoint 6% above ests
Zuckerberg ruled out voting-dilutive raise, Meta special committee says
[8:50 am] Meta’s special committee said Mark Zuckerberg would not back a significant equity raise that diluted his voting power, as the company races to fund its AI build-out.
-
Meta will issue new Class C shares via a one-time stock dividend of one Class C share for each Class A and Class B share, effective January 2027
-
On equity financing: “Mr. Zuckerberg made it clear… that he would not support a significant equity financing that would have the effect of reducing his voting power in the Company”
-
On funding conditions: “timing is important to secure capital before competitors saturate various funding options”
-
Muse signed up 10m+ users in six weeks across the US and Canada, with about 25% engaging daily, more than double Threads’ initial engagement
-
On Muse’s early adopters: “over 20% of U.S. Muse users today are $1,000-plus annual ARPU users”
-
Muse monetisation will start earlier than Meta’s usual playbook, with the company expecting it to eventually generate more revenue per US user than its Family of Apps
Good morning!
[8:27 am] ASX 200 futures are down 19 pts (-0.21%). Here’s what happened overnight:
-
AI spending fears returned with force as Meta’s cash burn and a chip equipment supply warning hammered megacaps, while defensives and the broader market held up
-
S&P 500 (-1.21%), Equal-weight S&P 500 (+0.73%)
-
Nasdaq (-2.60%), Dow (+0.02%) and Russell 2000 (+0.11%)
-
-
Commodities split on the Middle East, with Brent topping US$112 on deadly attacks in Saudi Arabia while gold, silver and copper extended a broad metals selloff
-
Bond traders slashed Fed hike bets ahead of next week’s meeting, sending the US 10-year yield back below 5% as investors sought havens